Menu
Date Published: April 6, 2023 (Updated November 4, 2026)
Table of contents :
TL;DR

A Christmas loan in Canada is a payday loan used to cover seasonal expenses such as gifts, groceries and travel. iCash, a licensed online lender operated by Finabanx Ltd., offers Christmas loans from $100 to $1,500 at a cost of $14 per $100 borrowed. Approved funds are sent by Interac e-Transfer, and the loan is repaid on the borrower’s next payday or in installments over up to 62 days, depending on the province.
It isn’t a separate product. It’s an everyday name for any borrowing used to cover December costs such as gifts, food, travel or a bill that lands before payday.
If you search for loans for Christmas, you’ll find existing products with a seasonal label, including installment loans from banks, credit cards, buy now, pay later plans and payday loans.
We offer payday loans. You can borrow a smaller amount starting at $100, up to $1,500. There’s no special rate, so you’ll pay the same $14 per $100 as the rest of the year. A payday loan works best for a small gap you can repay from your next paycheque, not for seasonal spending spread over several months.
You apply online, get a decision in minutes and, if you’re approved, receive the money by Interac e-Transfer. Repayment is taken from your bank account on your payday, in one payment or in installments, depending on your province.
Applying → You apply on the iCash website or app, choose how much to borrow and select a repayment plan. The application is available 24/7, including weekends and holidays.
Receiving funds → Our system gives you a loan decision within minutes, any time of day. If you’re approved, you sign your agreement electronically, and the funds are sent by Interac e-Transfer shortly after.
Repaying → Payments are withdrawn from your bank account by pre-authorized debit (PAD), timed to your paydays. Provincial payday loan regulations set how you repay: some provinces require one payment on your next payday, while others let you split the loan into smaller installments at the same cost.
Your agreement shows the exact dates and amounts before you sign, and you can repay early without penalty. Each province sets its own rules, so it’s worth knowing your rights as a payday loan borrower.
Note: You can only have one loan at a time, so you’ll need to repay your current balance before applying again.
Amount Borrowed | Cost of Borrowing | Total to Repay |
$100 | $14 | $114 |
$300 | $42 | $342 |
$500 | $70 | $570 |
$1,000 | $140 | $1,140 |
$1,500 | $210 | $1,710 |
On a 14-day term, $14 per $100 equals an annual percentage rate (APR) of 365%. Over 62 days, the same cost equals an APR of 82.42%. Our key terms page explains how APR is calculated on payday loans.
To qualify, you need to meet your province’s minimum age, live in a province we serve and have a steady income of at least $800 a month deposited into a bank account. No documents or paperwork are needed.
Age: be at least 18, or 19 in British Columbia, New Brunswick and Nova Scotia.
Province: live in Alberta, British Columbia, Manitoba, New Brunswick, Nova Scotia, Ontario or Prince Edward Island.
Steady income: have received income from the same source for the past three months. Employment, self-employment, government benefits, pension and disability income all count.
Minimum income: have a net income of at least $800 a month.
Bank account: have a bank account that accepts pre-authorized debits. KOHO accounts don’t qualify because they don’t support them.
Contact details: have a valid Canadian mobile number, home address and email address. VoIP numbers aren’t accepted.
Your first application includes a one-time credit check. After that, you skip it, so applying again as a returning customer is quicker.
Yes, you can apply with bad credit. We accept all types of credit and look at more than your credit history when reviewing an application. Your first application includes a credit check, but your score isn’t the only factor.
Here’s what else we look at:
Income amount: a net income of at least $800 a month that can cover the repayment.
Income stability: income from the same source for at least three months.
Affordability: an amount you can comfortably repay.
Meeting these points doesn’t guarantee approval, but it gives you a clearer picture of how borrowing with bad credit works. Keep in mind that Xmas loans can help with a cash gap, but it won’t fix credit problems. If debt is already building up, talking to a non-profit credit counsellor before you borrow may be a better first step.
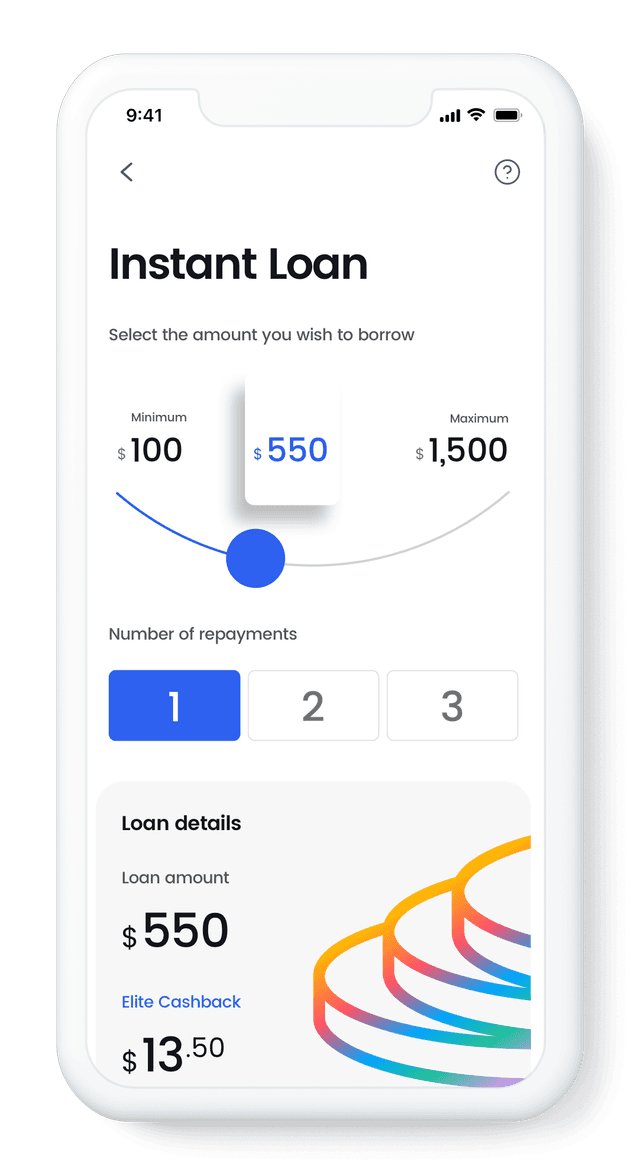
Getting an online loan with us is fast and easy. Simply select your loan amount, repayment plan* and provide some personal details.
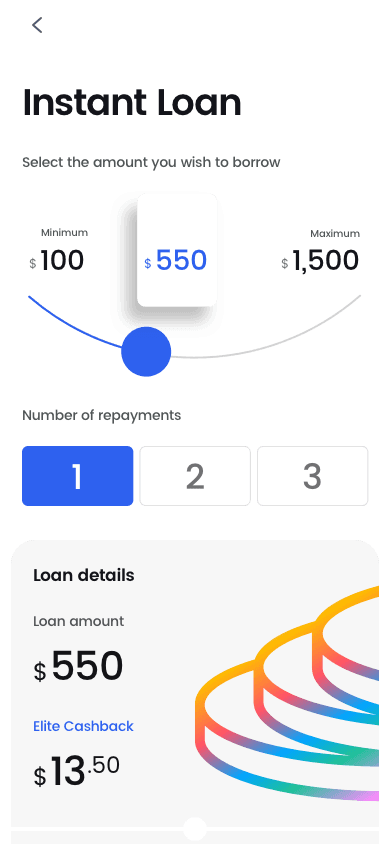
Our online loan application will tell you if you’re approved instantly. Once approved, all you have to do is electronically sign your contract. It’s that easy!
Once you sign your digital agreement, your cash advance will be sent by Interac e-Transfer® within 2 minutes. Fast, convenient and hassle-free. Funds are sent 24/7, no matter what.
The application is open 24/7, so you can apply for a loan on the weekend, or even on Christmas Day, and get a decision within minutes. With loans available around the clock, you won’t have to wait for a loan office to open.
While our application never closes, banks do. Here are this year’s bank holidays to plan around:
Christmas Day: Friday, December 25
Boxing Day: observed Monday, December 28
New Year’s Day: Friday, January 1, 2027
Use the table below to plan your funding, repayment and gift shipping around these dates.
Seasonal Planning | What to Know | What to Do |
Getting Your Funds | If you’re approved, we send your funds by Interac e-Transfer, available 24/7. | Apply as soon as you know you need the money. |
Repaying Your Loan | Payments are made by pre-authorized debit, which only processes on business days. | Check the repayment dates in your agreement before you sign. |
Mailing Gifts | Canada Post sets final posting dates for delivery before December 25. Check this year’s Canada Post holiday mailing deadlines before you order gifts. | If you’re borrowing for gifts, apply early. |
Before you borrow, it’s worth comparing other ways to cover seasonal costs. Some cost less but take longer to arrange, while others are quick but come with their own fees. The right choice depends on how much you need, how soon you need it and which options are open to you.
Cutting back in a few areas can also shrink the gap, and our money-saving tips for everyday spending are a good place to start. You can also consider these alternatives before you apply:
Using money you’ve set aside costs nothing and keeps January free of repayments. The trade-off is that savings take months to build, and using your emergency fund can leave you short later.
If you can pay the full balance by the due date, a credit card lets you spend now without interest. Carrying a balance or taking a cash advance adds interest and fees, so the cost grows over time.
If one is already set up on your bank account, it can cover a short gap. Applying for a new one usually means a review that can take days or weeks.
These plans split a purchase into smaller payments at participating retailers, often interest-free if you pay on time. They don’t cover rent or bills, and missed payments can bring late fees.
Some employers will advance part of your wages at little or no cost if you ask payroll or HR. The catch is a smaller next paycheque, which can make January tighter.
Picking up extra shifts at work or selling things you no longer use can raise cash without borrowing. Finding work or buyers takes time, so it works best if you start early.
Food banks, toy drives and hamper programs help families cover essentials at no cost. Many require registration before December, so check what’s available early.
This kind of borrowing suits you when you need a small amount quickly, can repay it from your next paycheque and the options above aren’t available. If that’s you, it’s worth choosing a lender that’s licensed in your province.
As a licensed online lender, we show you the full cost before you sign and send approved funds by Interac e-Transfer. Borrowing only what you need makes paying back easier, and our tips for planning your seasonal spending can help you work out that amount.
A little planning before you borrow makes the new year easier. Build a budget for the season to see how much you actually need, plan your payback date around January bills and watch for scams that peak in December. Our guide to borrowing responsibly with a payday loan has more ways to keep repayment manageable.
Start with what you plan to spend, then compare it with what you’ll have:
List your seasonal costs: gifts, food, travel, hosting and any bills due in December.
Work out what’s available: add up your December pay and subtract rent, utilities and other regular bills.
Trim where you can: set a gift limit, try a gift exchange or host a potluck.
Find the gap: any shortfall that remains is the most you should consider borrowing.
Example → Your next paycheque is $1,200. After rent and bills ($1,000), you have $200 left, which goes toward gifts and groceries. Then your car needs a $450 repair before you can drive to see family. Borrowing $450 would cover the repair for $63, so you’d repay $513 on your next payday.
Knowing the exact cost upfront helps you decide whether borrowing makes sense. You can see your total repayment with our loan cost calculator before you apply.
According to Spergel’s Financial Hangover Survey, 51% of Canadians carried new debt from the festive season into January 2026, and nearly 1 in 3 expected it to take six months or longer to recover financially. Knowing exactly when and how you’ll repay is one of the simplest ways to start the year on track.
To see where your repayment fits, list your paydays from early December to the end of January, then note your January bills beside them, such as rent, credit card statements and higher heating costs. Check that your payback date still leaves enough to cover the bills that follow it.
Try not to borrow again right after repaying. You’ll pay $14 per $100 each time, and borrowing back to back can make it harder to catch up. If January looks tight even with a plan, a non-profit credit counsellor can help you review your options.
Loan scams rise in December, when more people need quick cash. Scammers send fake offers by text, email, social media or lookalike websites.
Here are three red flags to look out for:
An upfront fee: legitimate lenders never ask you to pay before you get your money.
Guaranteed approval: no licensed lender can approve everyone.
No proof of licensing: lenders must be licensed in your province.
If something feels off, check with your provincial consumer protection office or the Financial Consumer Agency of Canada, and learn how to spot the warning signs of a lending scam.
Holiday budgets have a way of running out before the season does, and if yours comes up short, we’re here to help. You’ll know the cost upfront ($14 per $100 borrowed), you can apply 24/7 and approved funds arrive by Interac e-Transfer. Plus, returning customers skip the credit check next time.
iCash is a licensed online lender in Alberta, British Columbia, Manitoba, New Brunswick, Nova Scotia, Ontario and Prince Edward Island, and thousands of Canadians have shared their experience borrowing with us. Here’s to making the most of the season, one less worry at a time.
Since 2016, we've helped over 1.6 millions Canadians get instant loans online.
Since 2016, we've helped over 1.6 millions Canadians get instant loans online.
Read more reviews.
Have more questions? Check out our full FAQ.
Learn about your consumer rights and responsibilities in Canada, and how to protect yourself for fair and safe purchases.... Read more
Have you ever wondered if payday loans impact your credit score? It's a common question. Read below to learn the facts before applying for a payday loan.... Read more
e-transfer payday loans are a great way to get money fast for any financial emergency that may come up.... Read more